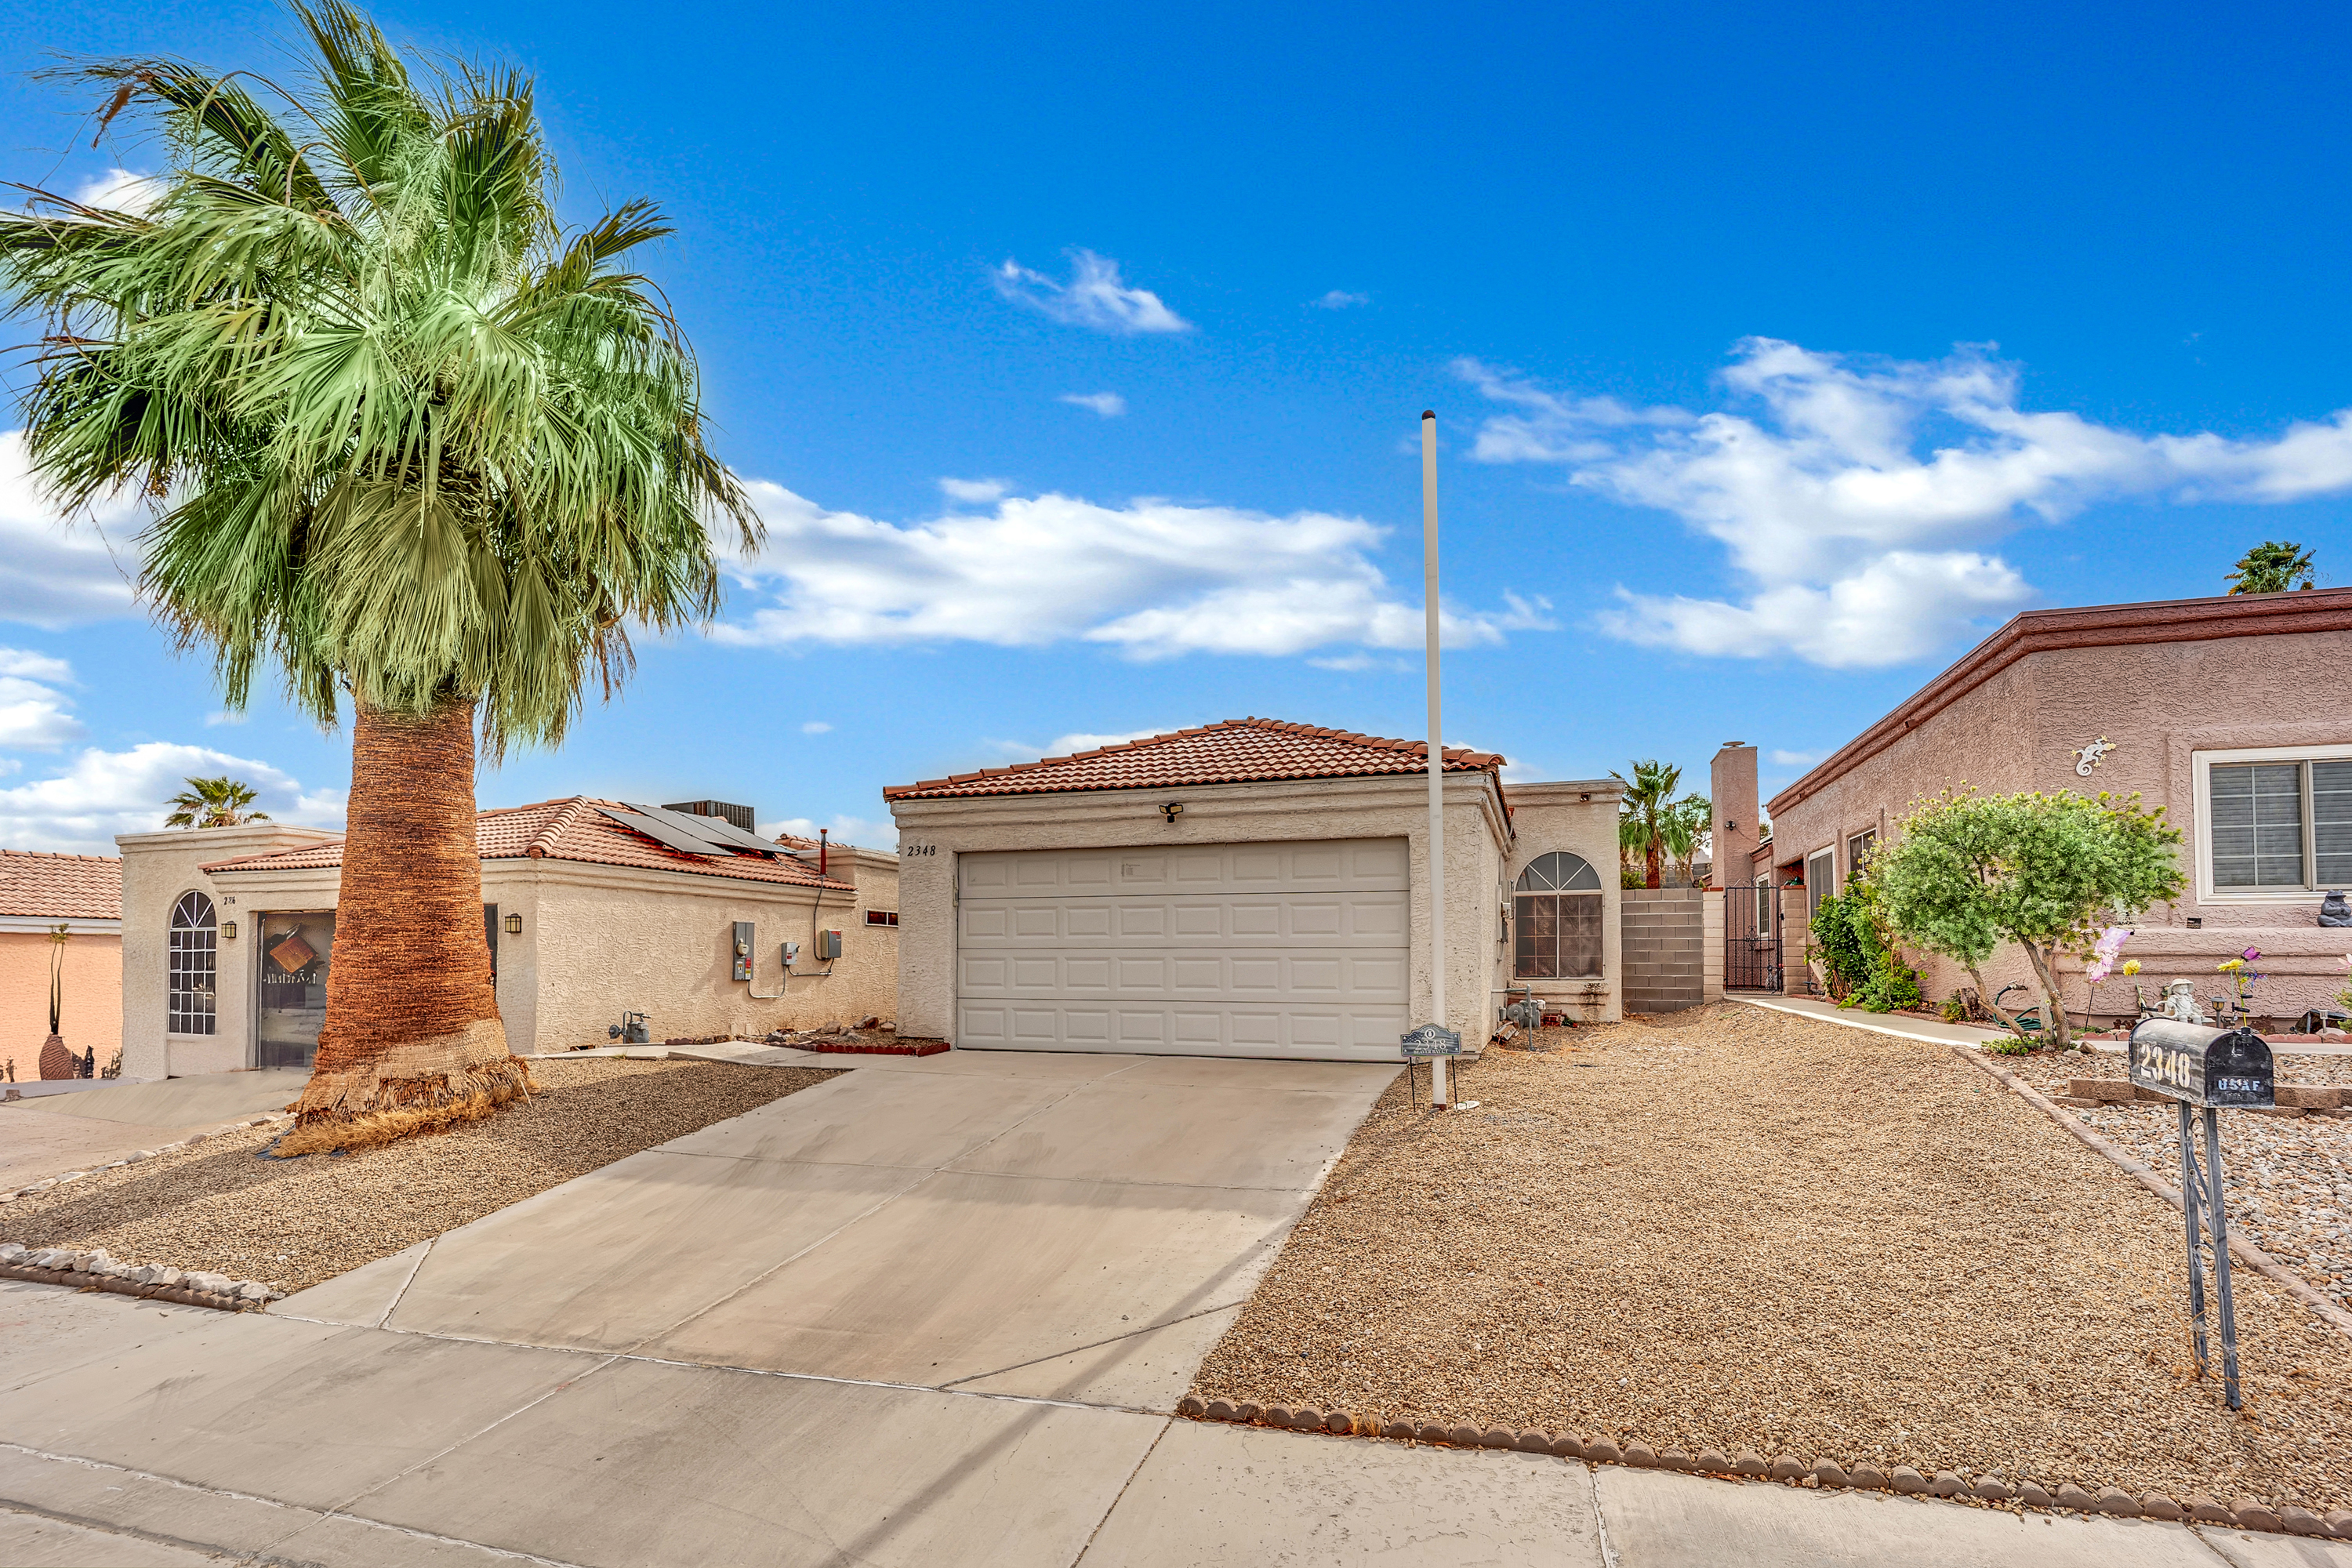
 2348 Beaver Bay Court · MLS #2808857
LAS VEGAS, NV 89156 · SINGLE STORY
2348 Beaver Bay Court
$374,9003 beds · 2 baths · 1,302 sq ft · 2-car garage
No HOAPaid-off solarCovered patio
A single-story home with vaulted ceilings, a gas fireplace, and a private backyard. Explore the photos and use the monthly payment calculator to see how the numbers fit your plans.
Listing courtesy of Kenneth R. Calder, You Decide Realty LLC. Marketed by Victor Gini, You Decide Referral. Confirm current price and availability with Victor.